
Global Asset Reshuffle in August: Gold Soars 9.7% to Lead, Agricultural Commodities Surge, Long-term Bonds Become Biggest Losers

Gold and agricultural products led the gains in August, with long-term bonds under pressure reaching multi-year highs, and the US dollar weakening for two consecutive months.
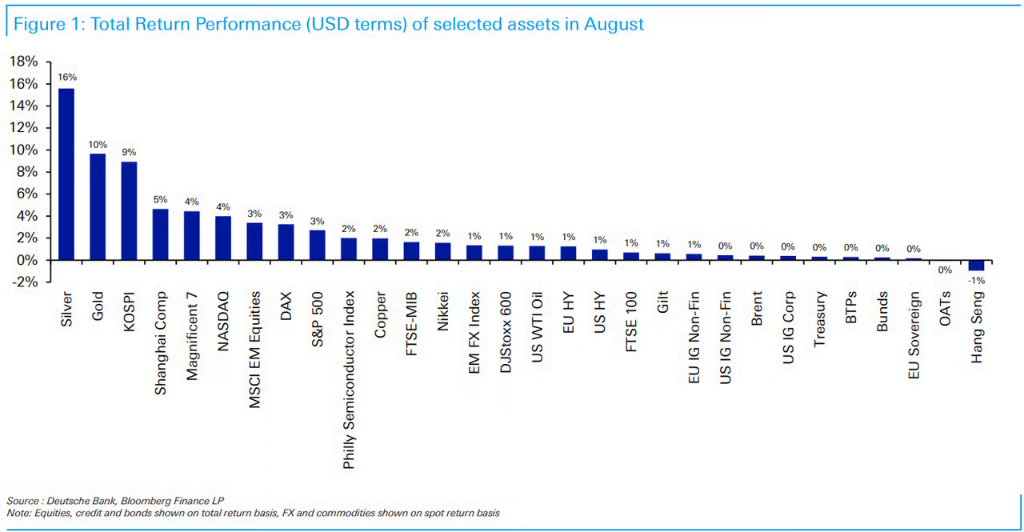
Global asset performance in August showed significant divergence. According to the latest monthly review report from Deutsche Bank, precious metals and agricultural products led the rally, with gold surging 9.7% in a single month and silver soaring 15.6%. Meanwhile, the continued blockade of the Strait of Hormuz and the El Niño weather pattern caused wheat, corn, and sugar futures to register their largest monthly gains in years. Supported by strong economic data and a robust earnings season, the equity markets steadily moved higher, with the S&P 500 Index rising 2.7% for the month.
However, not all markets followed this positive trend. Long-term bond yields across multiple major economies rose to multi-year highs, with the US 30-year Treasury yield briefly reaching its highest level since 2007. German and Japanese long-term bonds also came under pressure. The US Treasury unexpectedly announced a significant expansion of its long-term bond buyback program, briefly lowering long-end yields but also sparking concerns about "financial repression," further driving up gold and weakening the dollar.
Long-Term Yields Reach Multi-Year Highs, Bond Market Becomes Biggest Loser
The most closely watched market development in August focused on the sharp rise in global long-term government bond yields. According to Deutsche Bank data, the US 30-year Treasury yield rose to 5.31% on August 17, its highest since 2007. The German 30-year government bond yield hit 3.81% on August 31, the highest since 2011. Japan’s 30-year government bond yield reached 4.14% on August 18, the highest since the instrument was first issued in 1999.
There were multiple drivers for the rise in long-term rates. First, global growth expectations were optimistic—Eurozone’s August composite PMI preliminary reading rose to 52.1, the highest in nine months; US data climbed to 56.0, the highest in four years, reflecting strong economic resilience. Second, inflation pressures reignited as the ongoing closure of the Strait of Hormuz caused commodity, especially food, prices to rise sharply. Third, fiscal concerns returned to the spotlight.
Towards the end of the month, long yields saw a temporary pullback. On August 19, the US Treasury unexpectedly announced it would "at least double" the size of its long-bond buyback operations, raising the cap per operation from $2 billion to at least $4 billion. This move caught markets off guard, since just two weeks earlier the Treasury had released a tentative buyback plan for the quarter in its regular refinancing announcement.
From a market performance perspective, the European bond market underperformed overall. French, Italian, and German 10-year government bond yields respectively rose by 18, 13, and 12 basis points—significantly outpacing the US (+2 bps) and UK (+1 bp). In Japan, with rising market expectations for further rate hikes, the 10-year and 2-year bond yields increased by 15 and 23 basis points, respectively.
The US Treasury yield curve flattened overall. The 2-year yield rose 5 basis points during the month (with an 11 basis point jump after Jackson Hole comments last Friday), but the 30-year yield ended up edging down 3 basis points, causing the curve to flatten.
Gold and Silver Soar, Financial Repression Concerns Spark Safe-Haven Buying
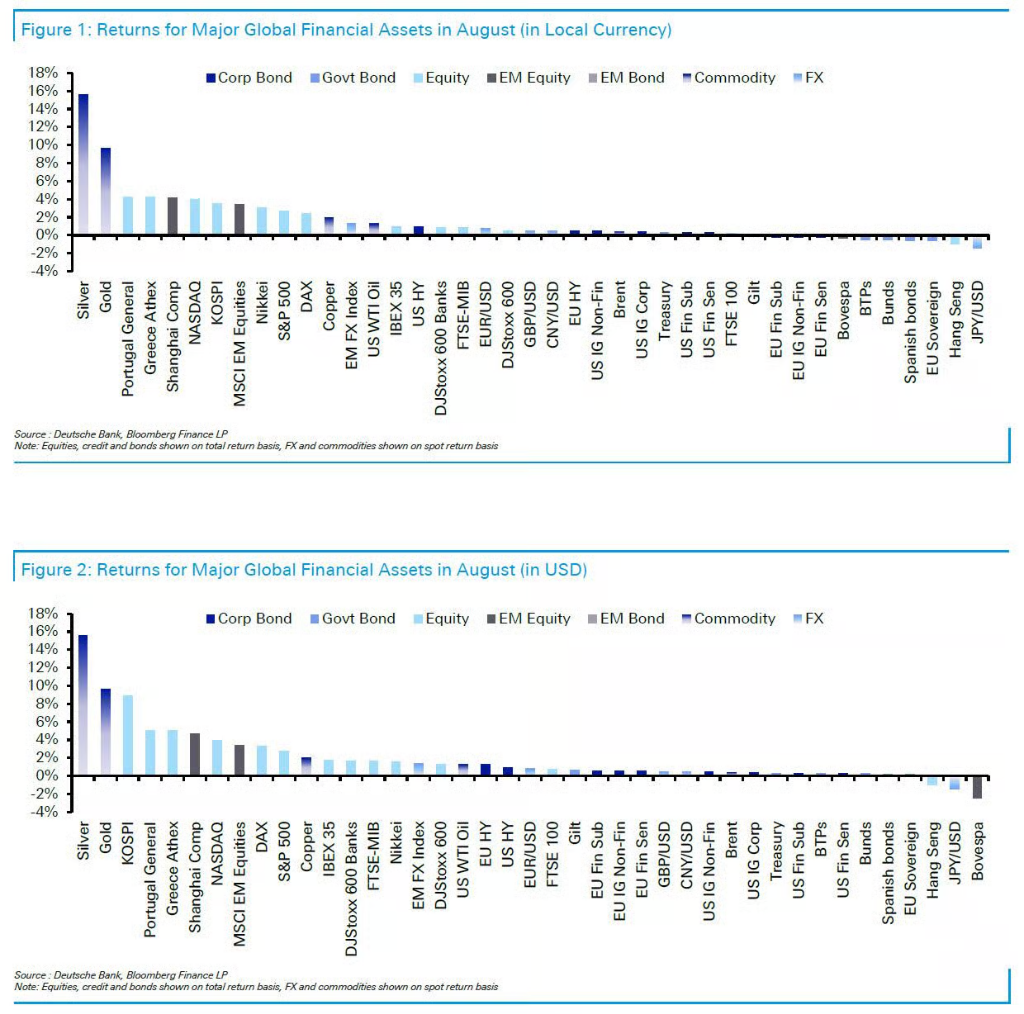
Precious metals were the best performing major asset class in August. Gold rose 9.7% in the month, closing at $4,437 per ounce; silver saw an even more notable gain, surging 15.6% and ending at $66.58 per ounce.
The core logic behind the precious metals rally was two-fold: first, rising inflation expectations; second, growing concerns about financial repression. The US Treasury’s substantial expansion of long-bond buybacks was interpreted by some market participants as a policy signal to suppress long-term rates, raising worries about erosion of monetary purchasing power. Meanwhile, the dollar index weakened by 0.5% in August, marking the second consecutive month of decline, which also provided extra support for precious metals denominated in dollars.
Agricultural Products Boom, Many Post Biggest Gains in Years
Food prices were another major focus in August. The ongoing blockade of the Strait of Hormuz combined with the El Niño weather pattern caused a sharp rise in agricultural futures.
Specifically, corn futures climbed 16.8% for the month, marking the largest monthly gain in five years; wheat advanced 18.3%, the strongest single-month performance in four years; sugar surged 21.5%, the biggest monthly rise since 2018. The concentrated breakout in agricultural products reflected both real supply-side disruptions and the market’s advance pricing of uncertainties surrounding future food supply.
Stock Markets Steadily Climb, Semiconductor Sector Becomes Calm
Despite pressures in the bond market, equities performed robustly overall in August. The S&P 500 Index delivered a total return of 2.7% for the month and set a new all-time high on August 13. The European STOXX 600 Index rose 0.5%, also reaching a record high on August 11, while the MSCI Emerging Markets Index climbed 3.4%, standing out comparatively.
At the sector level, technology stocks continued to lead gains. The S&P 500 Information Technology sector rose 6.2% in August, while the “Magnificent 7” tech giants as a group advanced 4.4%.
Notably, the Philadelphia Semiconductor Index gained just 2.0% in August—a marked stabilization compared to its double-digit volatility in both directions over the previous four months.
Oil Prices Close Slightly Higher, Geopolitics Still Dominate Narrative
The crude oil market was relatively steady in August, with Brent crude rising 0.4% to close at $90.49 per barrel—the smallest monthly fluctuation so far in 2024—while WTI crude rose 1.3% to $85.76 per barrel.
However, oil prices did not have a smooth ride during the month. At the beginning of August, Trump posted on social media that he had agreed to cancel planned attacks on Iran, leaving room for talks to resume, and Brent crude briefly dipped below $80 per barrel. Negotiations ultimately fell through, with Trump later saying “there are no talks or dialogues ongoing or scheduled,” and by the end of the month, renewed military clashes between the US and Iran sent oil prices rebounding.
Meanwhile, European natural gas futures surged 18.2% to close at €69.81 per megawatt hour, while US natural gas futures also climbed 6.8%.
Federal Reserve Remains Hawkish, Markets Bet on Rate Hike in September
Federal Reserve Chairman Waller’s remarks at the Jackson Hole symposium further influenced market expectations. His tone was more hawkish than anticipated, stressing that the Fed’s 2% inflation target is a “firm, fixed goal” and stating that although summer inflation data was better than expected, “it doesn’t tell me we’ve seen material improvement in the underlying trend.” After his speech, the US 2-year Treasury yield jumped 11 basis points in a single day and the yield curve flattened further. As of the end of August, futures markets priced a 65% probability of a rate hike in September, with investors generally betting that the Fed would continue tightening policy.
Disclaimer: The content of this article solely reflects the author's opinion and does not represent the platform in any capacity. This article is not intended to serve as a reference for making investment decisions.
You may also like
Will the traditional Christmas rally still happen in the US stock market this year?
After a simultaneous technical and position-based recovery in the US stock market, Goldman Sachs, Morgan Stanley, and JPMorgan have successively signaled a year-end rebound. Extremely light positions, mean reversion of valuations, and seasonal support together create conditions for a short squeeze. However, global manufacturing import price inflation has annualized at around 24%, surpassing the pandemic peak, and the inflation bill will come due intensively in the first quarter of next year. Goldman Sachs warns that once the year-end rally materializes, it may exhaust future upside potential.

Anthropic IPO Roadshow: CEO Says "Doesn't Care About Market Conditions", Hopes to "Underpromise and Overdeliver"
As Anthropic gears up for its IPO, CEO Amodei remains deliberately low-key during the roadshow, emphasizing "under-promise and over-deliver," and appears calm regarding market volatility at the time of listing. In response to fluctuations in the AI sector and the Nvidia situation, Amodei stated he is not particularly concerned about the specific month of listing or market conditions, and frankly admits that allocation of computing power is "the most fundamental business challenge."
SpaceX (SPCX.US) Starship's 15th Test Flight: Booster recovery failed for unknown reasons; first orbital round-trip mission still awaits upper stage "tower catch" landing
On Friday local time, SpaceX conducted its 15th Starship flight mission in Texas.

Unlike Elon Musk’s “One Price” Approach: Anthropic (ANT.US) Roadshow Pricing Inquiry at $70-78, Institutional Investors Become the True Decision Makers in IPO Pricing
Anthropic will launch what is set to be the largest IPO in history next week, aiming to take this title from SpaceX. However, unlike Elon Musk’s conglomerate, large investors will have greater influence over its IPO pricing amid the ongoing turbulence in the artificial intelligence (AI) market.
Crypto prices
More


