China has invested more than $120 billion in overseas mining and upstream processing since 2023, accelerating a state-backed push to secure the raw materials underpinning the global energy transition, says Australian think tank Climate Energy Finance (CEF).
A study published last week reveals that China’s spending targeted a wide range of commodities — including lithium, copper, nickel, rare earths and bauxite — that are essential for electric vehicles, renewable power and industrial decarbonization.
The scale of the push reflects what the authors describe as a coordinated strategy of “green energy statecraft,” in which Beijing is working to dominate not just resource extraction, but the full value chain that turns raw materials into battery-grade and industrial inputs.
Vertical integration at scale
The CEF research also finds that China’s outbound investment in mining is only one piece of a much larger industrial strategy.
Since early 2023, Chinese firms have also deployed more than $220 billion into downstream sectors such as battery manufacturing, electric vehicles, grids, solar and wind infrastructure, creating what researchers describe as a vertically integrated global cleantech expansion.
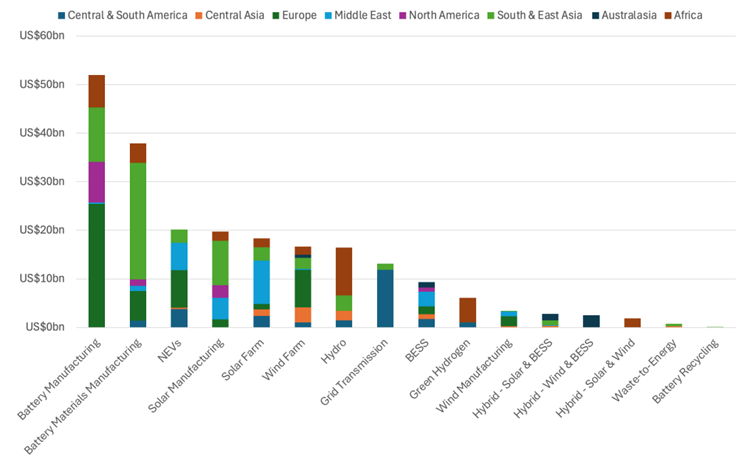 China’s cleantech OFDI by region (2023-2025). Source: CEF
Together, upstream resource investments and downstream manufacturing form a unified system designed to secure supply, reduce dependence on foreign inputs and reinforce China’s position at the center of the low-carbon economy.
That dominance is already evident. According to CEF estimates, China now controls about 90% of global rare earth refining, roughly 60% of lithium processing, more than 70% of cobalt refining and over half of global steel production. It also produces more than 90% of battery cathode and anode materials.
Africa and the Global South in focus
Much of China’s recent mining investment has flowed into resource-rich regions across Africa, Latin America and Southeast Asia.
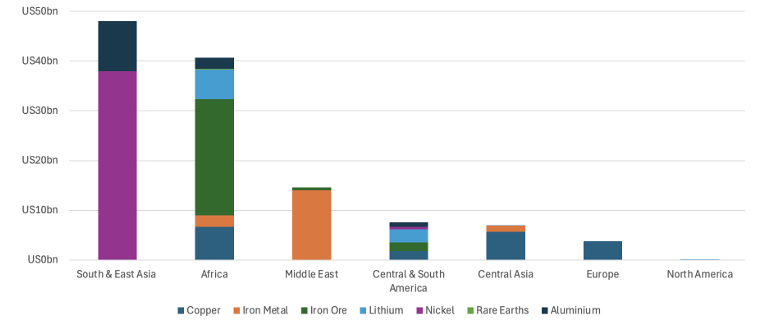 China’s FDI into mining and upstream processing (2023-2025). Source: CEF
In the Democratic Republic of Congo, Chinese companies have expanded their hold over copper and cobalt production, while in Indonesia, Chinese-backed investment has helped transform the country into the world’s largest nickel producer and processor.
Zimbabwe and other African nations have also seen rapid development of lithium mining and processing capacity backed by Chinese capital.
But the model has evolved. CEF analysis shows that Beijing is shifting away from the earlier Belt and Road approach — often criticized as extractive — toward a more collaborative framework.
Chinese firms are increasingly partnering with host governments to build in-country processing facilities, infrastructure such as railways, ports and power systems, and local industrial capacity, in exchange for long-term supply agreements, says CEF founder Tim Buckley, who co-authored the report.
This approach aligns China’s resource security goals with host countries’ ambitions to capture more value domestically and accelerate their own industrial development, he adds.
Supply chain control — and risk
China’s strategy is not just about access to raw materials, but about consolidating control over the entire supply chain.
By combining mining, processing and manufacturing, Beijing is strengthening its ability to influence pricing, availability and technology pathways in critical minerals markets, the CEF report notes, emphasizing that the trajectory remains one of expansion, not retreat, as China adapts its strategy to changing political and economic conditions.
Meanwhile, China’s growing market power is raising concerns among Western governments and industry players, who see growing risks to supply chain security and geopolitical stability.
Efforts to counterbalance China’s position are gaining momentum. Initiatives such as the US-led Minerals Security Partnership and the European Union’s Critical Raw Materials Act aim to diversify supply sources and rebuild domestic processing capacity.
A defining advantage
Still, replicating China’s scale and integration could take years.
As highlighted by CEF, China’s dominance is underpinned by a hybrid model that combines state direction with the speed and execution of private enterprise, supported by large-scale financing from state-backed institutions. For resource-rich nations, though, that model presents both risks and opportunities.
While dependence on a single dominant player raises strategic concerns, access to Chinese capital and technical expertise is also enabling faster development of mining, processing and infrastructure projects — particularly in emerging economies, the authors say.